
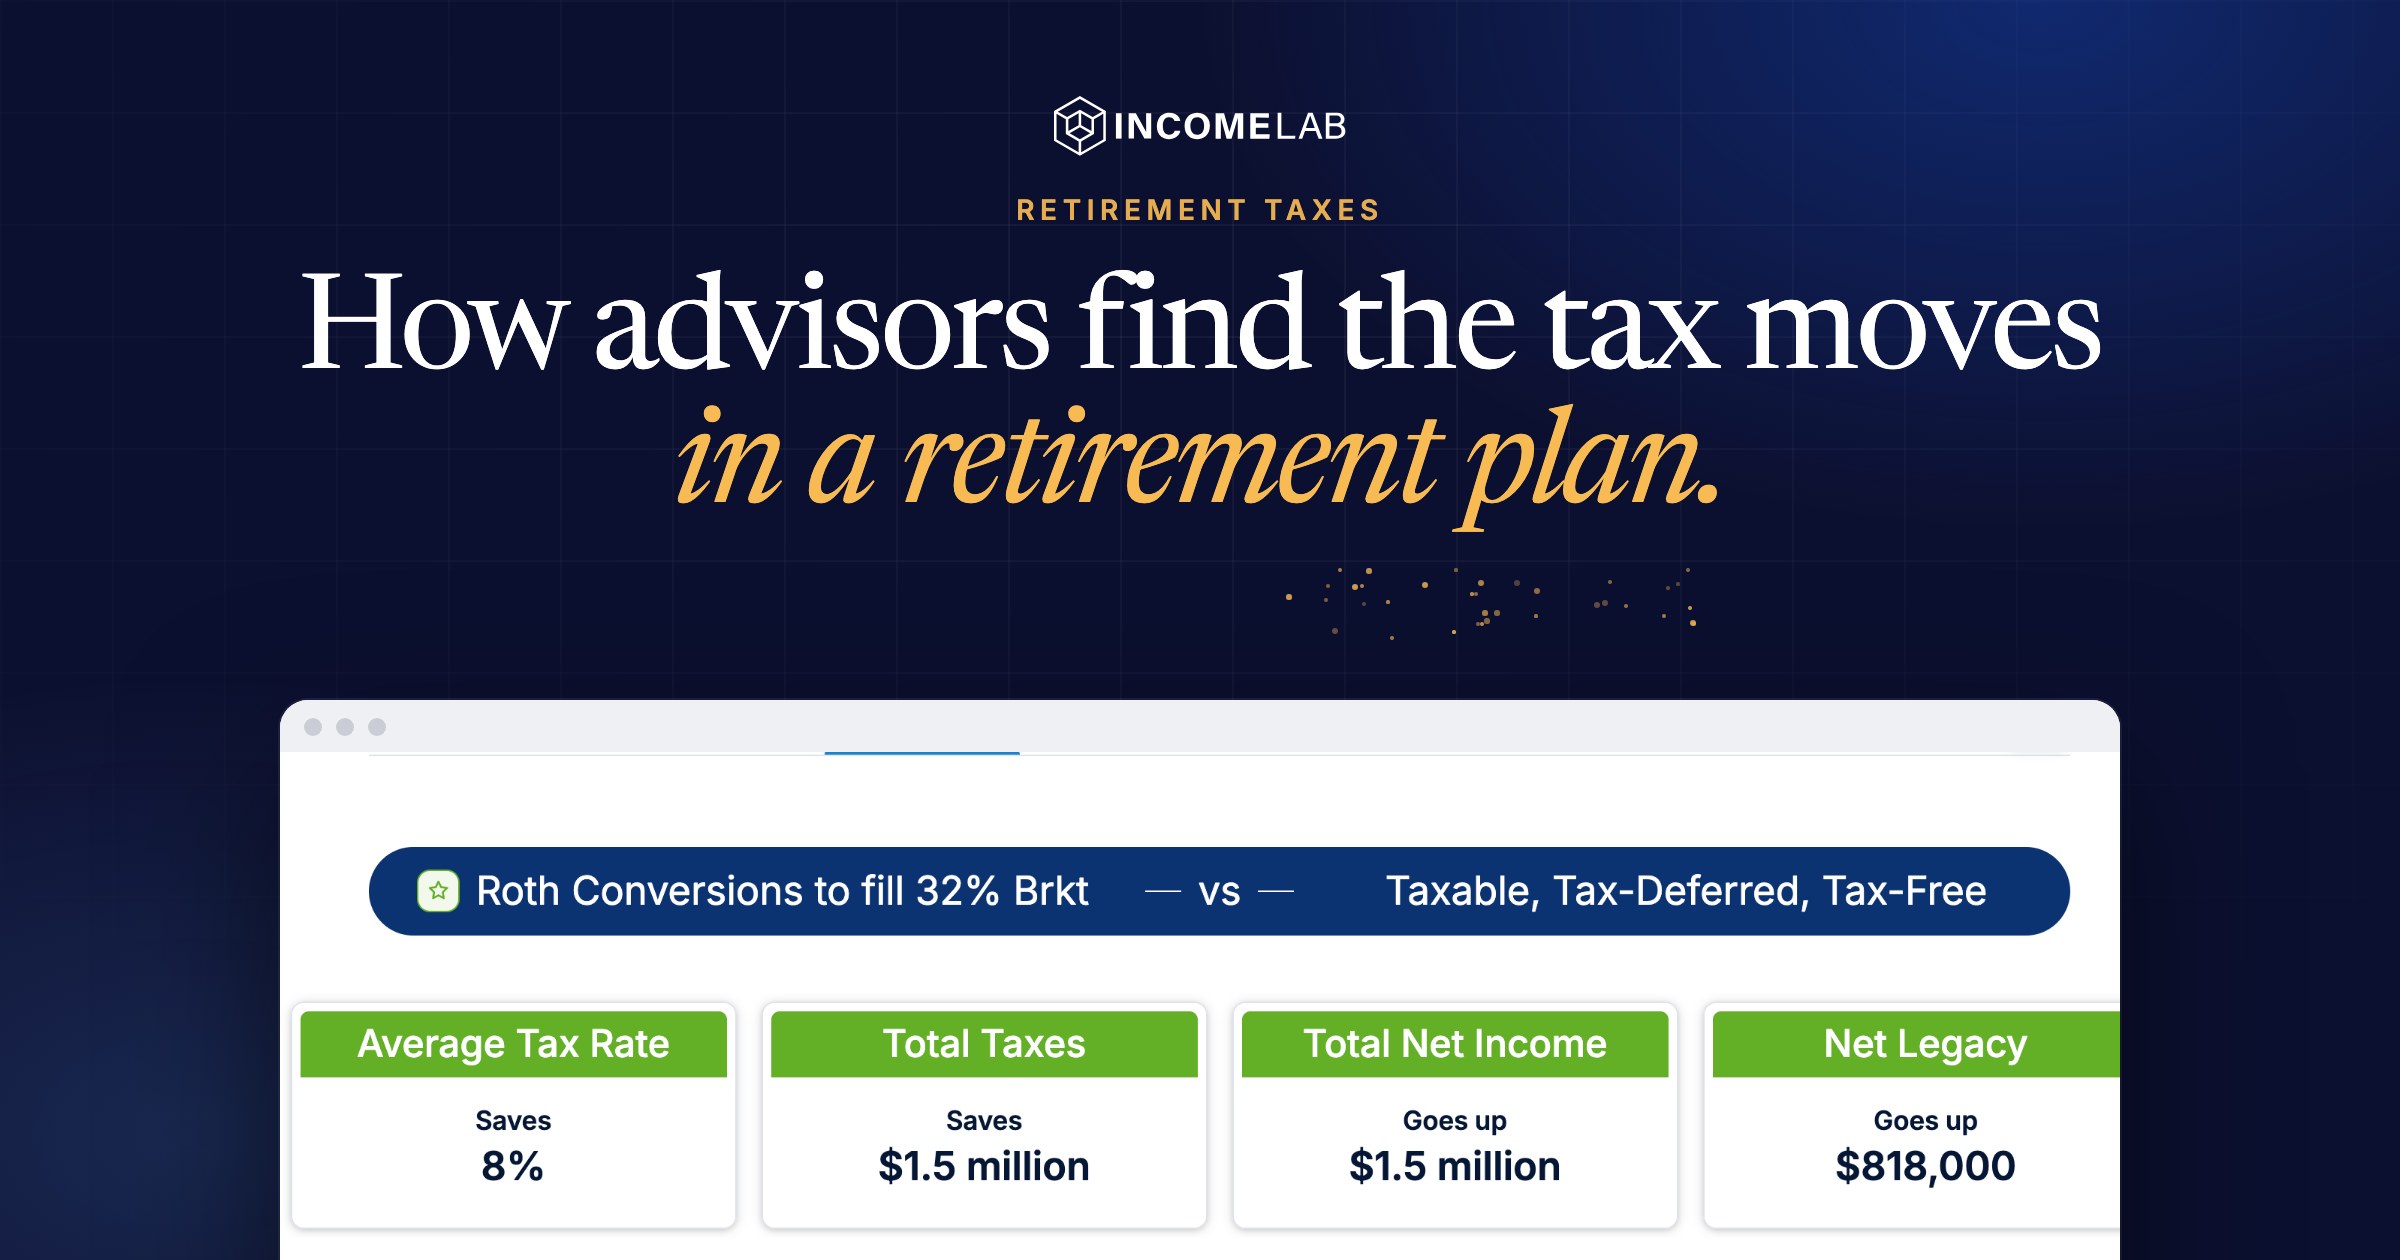
Consider a couple with $1.4 million invested: $900,000 in a traditional IRA owned by the older spouse, $350,000 in a taxable account, and $150,000 in a Roth IRA. The older spouse was born in 1959 and turns 67 in 2026; the younger spouse, born in 1962, turns 64. Their retirement plan supports spending of about $9,000 a month. The older spouse will generally begin required minimum distributions (RMDs) at age 73 in 2032. Between now and then, a relatively low-income period may provide attractive opportunities for Roth conversions. But the right amount to convert depends on much more than the tax bracket today. Future RMDs, Social Security benefits, Medicare premiums, portfolio withdrawals, and the taxes ultimately paid by beneficiaries can all change the calculation.
The advisor needs a way to find the opportunities worth examining, test their consequences over time, and explain the tradeoffs. That is the purpose of tax analysis integrated into a financial plan.
The five tax moves that matter in retirement
These five areas routinely deserve attention in retirement planning. Their value depends on the client’s circumstances and on how each decision affects the years that follow.
1. Roth conversions in the low-income window. The years after retirement and before RMDs begin can provide an opportunity to convert traditional IRA assets at relatively favorable rates. Income Lab can evaluate conversions across the projected lifetime tax picture, including when Social Security starts, how spending is funded, and what happens to the assets remaining at death. A conversion that raises taxes this year may still improve the client’s lifetime result or the after-tax amount that gets to heirs.
2. The ACA credit hurdle. If someone retires before Medicare is available (before age 65) and is receiving ACA credits, they may be best served by delaying Roth conversions until the ACA window is closed. This is another reason why different parts of the financial plan need to be connected: work-to-Medicare transition planning and Roth conversion planning.
3. Medicare IRMAA tiers, on the two-year MAGI lookback. A Roth conversion, realized gain, or other income event can push modified adjusted gross income (MAGI) across a Medicare premium threshold. The consequence generally arrives two years later and may affect both spouses. A useful comparison includes the estimated surcharge alongside the potential long-term tax benefit; avoiding IRMAA in every year is not necessarily the best strategy.
4. Withdrawal sequencing. The accounts used to support spending affect taxable income today and the balances and tax exposure left for later years. Taxable, tax-deferred, and Roth assets interact differently with the client’s tax brackets and other income. Retaining IRA funds over 401(k) funds to allow for future tax-efficient qualified charitable distributions (QCDs), preferring distributions from an older spouse’s accounts, and more can all affect the overall plan.
5. Qualified charitable distributions from IRAs. Starting at age 70½, an eligible client can make a qualified charitable distribution (QCD) directly from an IRA. QCDs can satisfy all or part of an IRA RMD and generally exclude the distributed amount from adjusted gross income. The benefit depends on the client’s charitable intentions, RMDs, other income, and alternatives such as donating appreciated securities.
| Move | The decision | Why it hides from a return-first analysis | Age gate |
|---|---|---|---|
| Roth conversions in the low-income window | Whether and when to convert | The window is defined by future Social Security and RMD timing | Before the owner’s RMDs begin (73 or 75 by birth year) |
| Bracket management | How much to convert each year | Needs the multi-year bracket path, not one return | Same window |
| IRMAA tiers | What each income decision does to Medicare premiums | The cost lands two years later, on the MAGI lookback | 63 and older |
| Withdrawal sequencing | Which account funds each year’s spending | Depends on the client’s bracket path across the plan | All of retirement |
| Qualified charitable distributions | Give from the IRA instead of cash | Value depends on RMD position and IRMAA tier | Age 70.5 |
Advisor takeaway
A tax opportunity is only useful when it improves an outcome the client cares about. Evaluate the combined impact on spendable income, lifetime taxes, Medicare premiums, and after-tax assets, not simply the tax saved in one year.
Why a full plan uncovers the opportunities
Many advisors begin tax planning with a tax return. But many of these opportunities depend on the years ahead. A tax return establishes what happened in a prior year. It is useful, no doubt, but it is a historical document. To decide whether to convert now, accelerate income, or draw from a different account, the advisor also needs a view of projected earnings, Social Security, spending, RMDs, investments, and beneficiaries.
Dedicated tax planning software may project several years ahead and identify important opportunities. The challenge is keeping those projections aligned with the financial plan as the client’s circumstances change. A plan-integrated approach starts with the income, spending, account, and investment assumptions already being used for retirement planning. Income Lab’s Tax Lab uses those assumptions to evaluate strategies over time, reducing the duplicate entry and reconciliation otherwise required.
That integration also improves the conversation. An advisor can see a low-income window in the projected tax picture, examine the reasons for it, model a strategy, and compare the resulting tax and financial outcomes. The analysis becomes part of an ongoing planning review rather than an isolated year-end exercise.
A Roth conversion and IRMAA example, in dollars
Assume the couple in the example above file jointly and project 2026 MAGI of $196,000 before a Roth conversion. Their advisor is considering conversions of $22,000 and $100,000.
The Medicare threshold. Under the published 2026 schedule, the first IRMAA threshold for a married couple filing jointly is $218,000 of MAGI. With projected MAGI this year of $196,000, the couple has $22,000 of room below that threshold. This is a useful reference point, although it is not necessarily the right limit for the conversion.
A smaller conversion. A $22,000 Roth conversion brings projected MAGI to $218,000. If all of the conversion is subject to a 22% marginal federal rate, the incremental federal tax would be about $4,840, before state taxes and other possible interactions. Under the illustrative 2026 IRMAA thresholds, it would not move the couple into a higher premium tier. (Actual 2028 IRMAA thresholds will be determined based on inflation between 2026 and 2028.)
A larger conversion. A $100,000 conversion brings MAGI to $296,000, which falls in the second IRMAA surcharge tier under the published 2026 schedule. At that tier, the additional Part B and Part D premiums would total approximately $5,770 for a full year for two Medicare beneficiaries, using 2026 amounts. The actual 2028 cost could differ. The larger conversion might nevertheless be preferable if it reduces future RMDs, taxes on later distributions, or taxes borne by heirs enough to outweigh the earlier tax payment and Medicare cost.
A credible comparison carries the alternatives through future years, including the investment growth forgone when conversion taxes are paid, the accounts used to pay those taxes, and the balances remaining at death. The question is whether the strategy improves the client’s overall result, rather than whether it stays below a single threshold.
Advisor takeaway
IRMAA is a cost to include in the decision, not an automatic reason to avoid a conversion. Show the client what crossing a tier costs and how that compares with the projected longer-term benefit.
How to show it to the client
The best explanation starts with the client’s financial plan and follows the effects of a proposed change.
In Tax Lab, advisors can show projected income in relation to tax brackets and Medicare IRMAA thresholds, then compare strategies and their results. The graphs help explain why a conversion might make sense in a lower-income year and what changes after Social Security or RMDs begin. The broader analysis can also show effects on future spending resources and net legacy at different points in the plan.
Use concrete numbers, but put them in context. For example: “Converting $22,000 would generate roughly $4,840 of federal tax under these assumptions and stay below the illustrated Medicare threshold. We should compare that with a larger conversion and see what each does to future taxes and the assets you will have later.”
As with so much of financial planning, the right answer isn’t always perfectly clear, and different clients will have different priorities and preferences. Someone who cares greatly about net-of-tax legacy may care more about Roth conversions. Someone who hates paying more tax now, no matter the possible future gain, may simply care less to engage in conversions.
Common mistakes
Treating 50% or 85% as a tax rate. The 50% and 85% numbers we see around Social Security taxation refer to the portion of benefits that may be included in taxable income. They are not federal income tax rates. As other income changes, more Social Security benefits can become taxable, sometimes making the effective marginal tax rate higher than the statutory bracket suggests.
Making the conversion decision one year at a time. A conversion that raises current taxes can reduce later RMDs and the taxable value of assets inherited by beneficiaries. The analysis should compare results over multiple years, including the effects on investment balances, Medicare premiums, and spending.
Assuming avoiding IRMAA is always best. The Medicare surcharge associated with additional income can be significant, and it is generally determined using tax information from two years earlier. It belongs in the cost of a strategy, but a higher-premium year can be worthwhile if the overall benefit is larger. Also, the tax year and premium year may use different thresholds and premium schedules.
Ignoring how conversion taxes are paid. Paying tax from a taxable account, income, or retirement assets can change the long-term value of a Roth conversion. Tax Lab uses defined assumptions for how those taxes are funded, and net legacy values (or, alternatively, total net amounts to clients and heirs) include these taxes, accounting for lost gains on the funds used to pay taxes.
Overlooking qualified charitable distributions (QCDs), especially before RMDs begin. For clients eligible to make QCDs who already plan to give to charity, using an IRA distribution can reduce adjusted gross income and may satisfy an RMD and provide incredibly valuable “triple tax free” treatment. The benefit should be compared with other ways to make the gift. Since QCD eligibility stayed at age 70.5 while RMD ages went up, it is common for the period between 70.5 and 73 or 75 to be overlooked for QCDs.
How Income Lab surfaces these moves
Income Lab brings tax strategy analysis into the same model used to plan retirement income. The advisor can identify opportunities based on projected cash flows and account balances, test alternatives, and understand their implications for the client’s spending and legacy goals.
Tax Lab compares strategies using multi-year tax projections and measures such as net income and net legacy. Advisors can evaluate Roth conversions, bracket-based and IRMAA-aware approaches, and different sources of retirement withdrawals. The analysis takes account of projected Social Security, RMDs, spending, and other income from the plan, rather than requiring the advisor to recreate those assumptions in a separate tax tool. Penny can also help advisors explore questions using the client’s plan, with changes reviewed and approved by the advisor.
The advantage is consistency. Changes to retirement dates, earnings, Social Security claiming, or spending assumptions can change the tax opportunities worth pursuing. Because those decisions are modeled together, advisors can revisit the tax strategy as the plan evolves and see how the alternatives affect the household’s overall finances. For a client, the result is a clearer discussion of why a particular move matters and how much difference it may make.
Frequently asked questions
What are the biggest tax moves for a new retiree?
For many clients, Roth conversions in lower-income years, bracket management, IRMAA-aware decisions, retirement withdrawal strategy, and qualified charitable distributions deserve consideration. The most valuable move depends on projected income, spending, assets, future RMDs, and the after-tax legacy goal.
Why does some tax software miss these moves?
A tax analysis needs forward-looking assumptions about earnings, Social Security, RMDs, withdrawals, and spending. Dedicated tax software often starts (or even ends) with a historical tax return, or requires you to recreate future plans imperfectly to enhance the analysis. Tax analysis that is fully integrated with the financial plan can use the same assumptions and adjust as the plan changes.
When does IRMAA, with its two-year MAGI lookback, start to matter for a client?
Because premiums generally reflect MAGI from two years earlier, a client’s income decisions can affect Medicare premiums before the client enrolls. Age 63 is a useful planning checkpoint for someone expecting Medicare at 65, although the relevant income years and exceptions depend on the client’s circumstances. In some cases, IRMAA appeals for life-changing events can push the first year forward from 63 to 64 or 65.
Do I need to be a tax expert to run these conversations?
No. But advisors need to recognize possible opportunities, understand the tradeoffs, and know when to involve a tax professional. Software can perform multi-year calculations and comparisons, while the advisor evaluates whether the strategy fits the client’s priorities. Real tax advice belongs with tax professionals, so coordinating and communicating these ideas is vital.
Should the client’s CPA be involved?
Yes. Tax planning works best when the advisor and CPA coordinate on projected strategies, implementation details, and current-year tax results. Planning estimates should be checked against the client’s actual tax situation before transactions are executed.
Sources
-
CMS, 2026 Medicare Parts A and B Premiums and Deductibles. Source for the 2026 IRMAA thresholds ($218,000 joint) and the tier surcharge figures used in the worked example, applied on the two-year MAGI lookback.
-
Social Security Administration, Premiums: Rules for Higher-Income Beneficiaries. Source for the two-year lookback rule.
-
IRS, Retirement plan and IRA required minimum distributions FAQs. Source for RMD timing and the IRA-only scope of qualified charitable distributions.
-
IRS, IRC Section 86 rules on taxation of Social Security benefits (Publication 915). Source for the combined-income thresholds and the 50% and 85% taxability caps.
-
Income Lab Help Center, Tax Lab methodology, strategy ranking, bracket management, and IRMAA bracket management articles, re-verified at the live help center September 23, 2026. Source for the parallel strategy comparison, the net income and net legacy ranking, bracket management mechanics, IRMAA bracket management and its estimated premium costs, the conversion tax waterfall, and the state tax treatment language.
All trademarks are property of their respective owners.
Continue Reading
Ready to see this in action?
Watch how Income Lab helps advisors answer clients' toughest retirement income questions with guardrails-based planning.
Book a Walkthrough Start Free Trial