
A client calls in March. The roof needs replacing, the estimate is $60,000, and they want the money in three weeks. They are 68, married, and retired. Their investments include taxable brokerage holdings, traditional IRAs, and a Roth IRA. They want to know where the money should come from.
The advisor has several decisions to make before placing a trade: how much cash must actually reach the client, which accounts can supply it, which holdings to sell, how much tax the sales and distributions will create, and whether the choices still make sense in the context of the plan.
A simple cash request creates several decisions
An IRA distribution might be operationally easy, but funding the full $60,000 from pre-tax assets can create a much larger taxable distribution. The advisor also needs to consider whether selling taxable holdings would realize gains or losses, whether particular positions should be retained, and whether the client already has planned distributions for the year.
For illustration, if the entire $60,000 must be delivered after federal tax and the incremental traditional IRA distribution is taxed at a constant 22%, the gross distribution would be about $76,900, with about $16,900 of federal tax. (This simplified gross-up excludes state tax and interactions that could change the marginal rate.)
The impact may extend beyond the current tax return. If household modified adjusted gross income (MAGI) was otherwise expected to be $175,000, that distribution could lift it to roughly $251,900. In this illustration, that crosses the first 2026 Medicare IRMAA threshold for a married couple filing jointly ($218,000). Medicare generally uses a two-year income lookback, so the effect would emerge in premiums two years later. Using the published 2026 premium schedule only as an illustration, the first-tier incremental cost for the couple is approximately $2,297 annually; the actual future schedule will differ.
The account and holdings chosen therefore affect more than the tax on this withdrawal. They can also change future Medicare premiums and the assets available for later spending.
The advisor’s task is to deliver the requested cash while making the related tax, portfolio, and planning consequences visible.
What the advisor needs to consider
A useful approach brings the following questions into the same analysis rather than evaluating each account in isolation.
Accounts and ordinary income. Distributions from fully pre-tax traditional IRAs and employer retirement accounts generally create ordinary income. Any after-tax basis needs separate treatment. Existing withdrawals, expected income, and required minimum distributions (RMDs) affect the additional tax cost.
Holdings and realized gains. In a taxable account, the advisor needs to know the cost basis of the specific lots being sold. High-basis positions may provide cash with little realized gain, while selling losing positions may offset gains. In some years, harvesting gains within the 0% long-term capital gains bracket may also be useful.
Tax thresholds and Medicare. Additional income can change ordinary-income and capital-gain rates, Social Security taxation, the net investment income tax, deductions or credits, and Medicare IRMAA. A small change in a sale or distribution can have a disproportionate consequence near a threshold.
Investment implications. Selling a holding changes the remaining portfolio. The advisor may want to protect certain positions, limit sales from a concentrated or illiquid holding, preserve an allocation, or use a withdrawal to rebalance. The tax-minimizing sale is not necessarily the preferred investment decision.
Longer-term plan effects. Spending Roth assets today gives up future tax-free growth; using high-basis taxable lots changes the gains embedded in what remains. The client’s cash need has to fit alongside future spending, expected returns, charitable plans, and other transactions already anticipated for the year.
Choosing the accounts and holdings
There is no universal ranking of accounts that settles this decision. The advisor should evaluate the incremental cost of alternative mixes of accounts and individual holdings, with the financial plan and portfolio constraints in view. These are common inputs to that analysis:
| Possible source | Information to evaluate | How it can affect the choice |
|---|---|---|
| Cash or money market | Liquidity and planned cash reserves | Available cash may avoid selling investments, provided reserves remain adequate |
| Taxable holdings | Specific lots, basis, gains and losses | High-basis lots and harvested losses may reduce the tax cost of sales |
| Traditional IRA or employer plan | Ordinary tax, RMDs, distribution restrictions | May be appropriate in a lower-income year or when distributions are already required |
| Qualified Roth assets | MAGI or bracket management and future tax-free growth | Can limit current-year income but reduces assets retained for later years |
Several additional considerations can materially change the recommendation.
Take RMDs first. When required distributions remain for the year, they are part of the cash-flow picture. The advisor should account for amounts already taken or earmarked, and for IRA RMD aggregation rules where applicable, before deciding how to meet an additional cash request.
Taxes, MAGI limits, and tapping Roth accounts. An advisor may want to manage ordinary taxable income, long-term gains, Medicare IRMAA MAGI, or ACA MAGI. While advisors will typically avoid taking withdrawals from Roth accounts, these ceilings can justify tapping Roth funds now (and therefore giving up future tax-free growth on those assets) in order to avoid major current taxes, loss of ACA credits, or future IRMAA.
Loss and gain harvesting. Tax-lot selection can offset gains with losses and may make use of available 0% long-term gains capacity. The appropriate transactions depend on the client’s actual holdings and tax situation.
Charitable giving and withholding. A planned qualified charitable distribution from an IRA or a donation of appreciated securities can affect the best use of available assets. The advisor also needs a practical plan for withholding or estimated payments, including whether the requested amount is net cash or a gross withdrawal.
The result should specify amounts by account and holding, with the estimated tax consequences and payment instructions made clear.
The $60,000 roof expense: comparing two approaches
Consider a hypothetical household to see how these choices work together. The illustration isolates selected federal tax and Medicare effects and does not represent a recommendation for a particular client.
Assumptions: a married couple, both 68, filing jointly; projected 2026 MAGI of $175,000 before the additional withdrawal; a constant 22% incremental federal ordinary rate; no state income tax; no RMD due; fully pre-tax IRA dollars; qualified Roth distributions; and $5,000 of available embedded losses in a taxable account. The goal is $60,000 in spendable cash. For comparability, the Medicare effect is illustrated using 2026 IRMAA figures, although the actual surcharge year would use a future schedule.
| Path | Gross withdrawn | Federal tax | Year-end MAGI | Medicare effect |
|---|---|---|---|---|
| All from the IRA | $76,900 | about $16,900 | about $251,900 | Crosses the first tier, about $2,297 for the couple on the 2026 schedule |
| Combined sources | $67,900 | about $7,900 | about $210,900 | Stays under the $218,000 threshold |
One possible approach combines three sources. Sell $20,000 of high-basis taxable holdings with approximately $5,000 of long-term gains, offset by realizing $5,000 of available losses. Take $12,000 of qualified Roth distributions. Then distribute about $35,900 from the traditional IRA to provide $28,000 after the assumed $7,900 federal tax. Together, the sources deliver $60,000 of spendable cash. The Roth portion matters here because replacing it with additional IRA income would bring illustrative MAGI above the Medicare threshold.
Under those assumptions, the combined approach produces roughly $7,900 of incremental federal tax, compared with roughly $16,900 if all the cash comes from the IRA. Illustrative MAGI remains near $210,900, below the stated threshold, rather than rising to about $251,900. The tradeoff is the use of $12,000 of Roth assets and the changes to the remaining taxable portfolio.
The advisor still has to judge whether that tradeoff is appropriate given the household’s investments, future tax outlook, and other anticipated cash needs. The example shows why account selection alone is insufficient without holdings and plan information. It also shows why, even for advisors who do not otherwise focus on financial planning, a basic plan with visibility to this year’s income is indispensable to giving good advice.
How Penny’s Withdrawal Optimizer approaches the problem
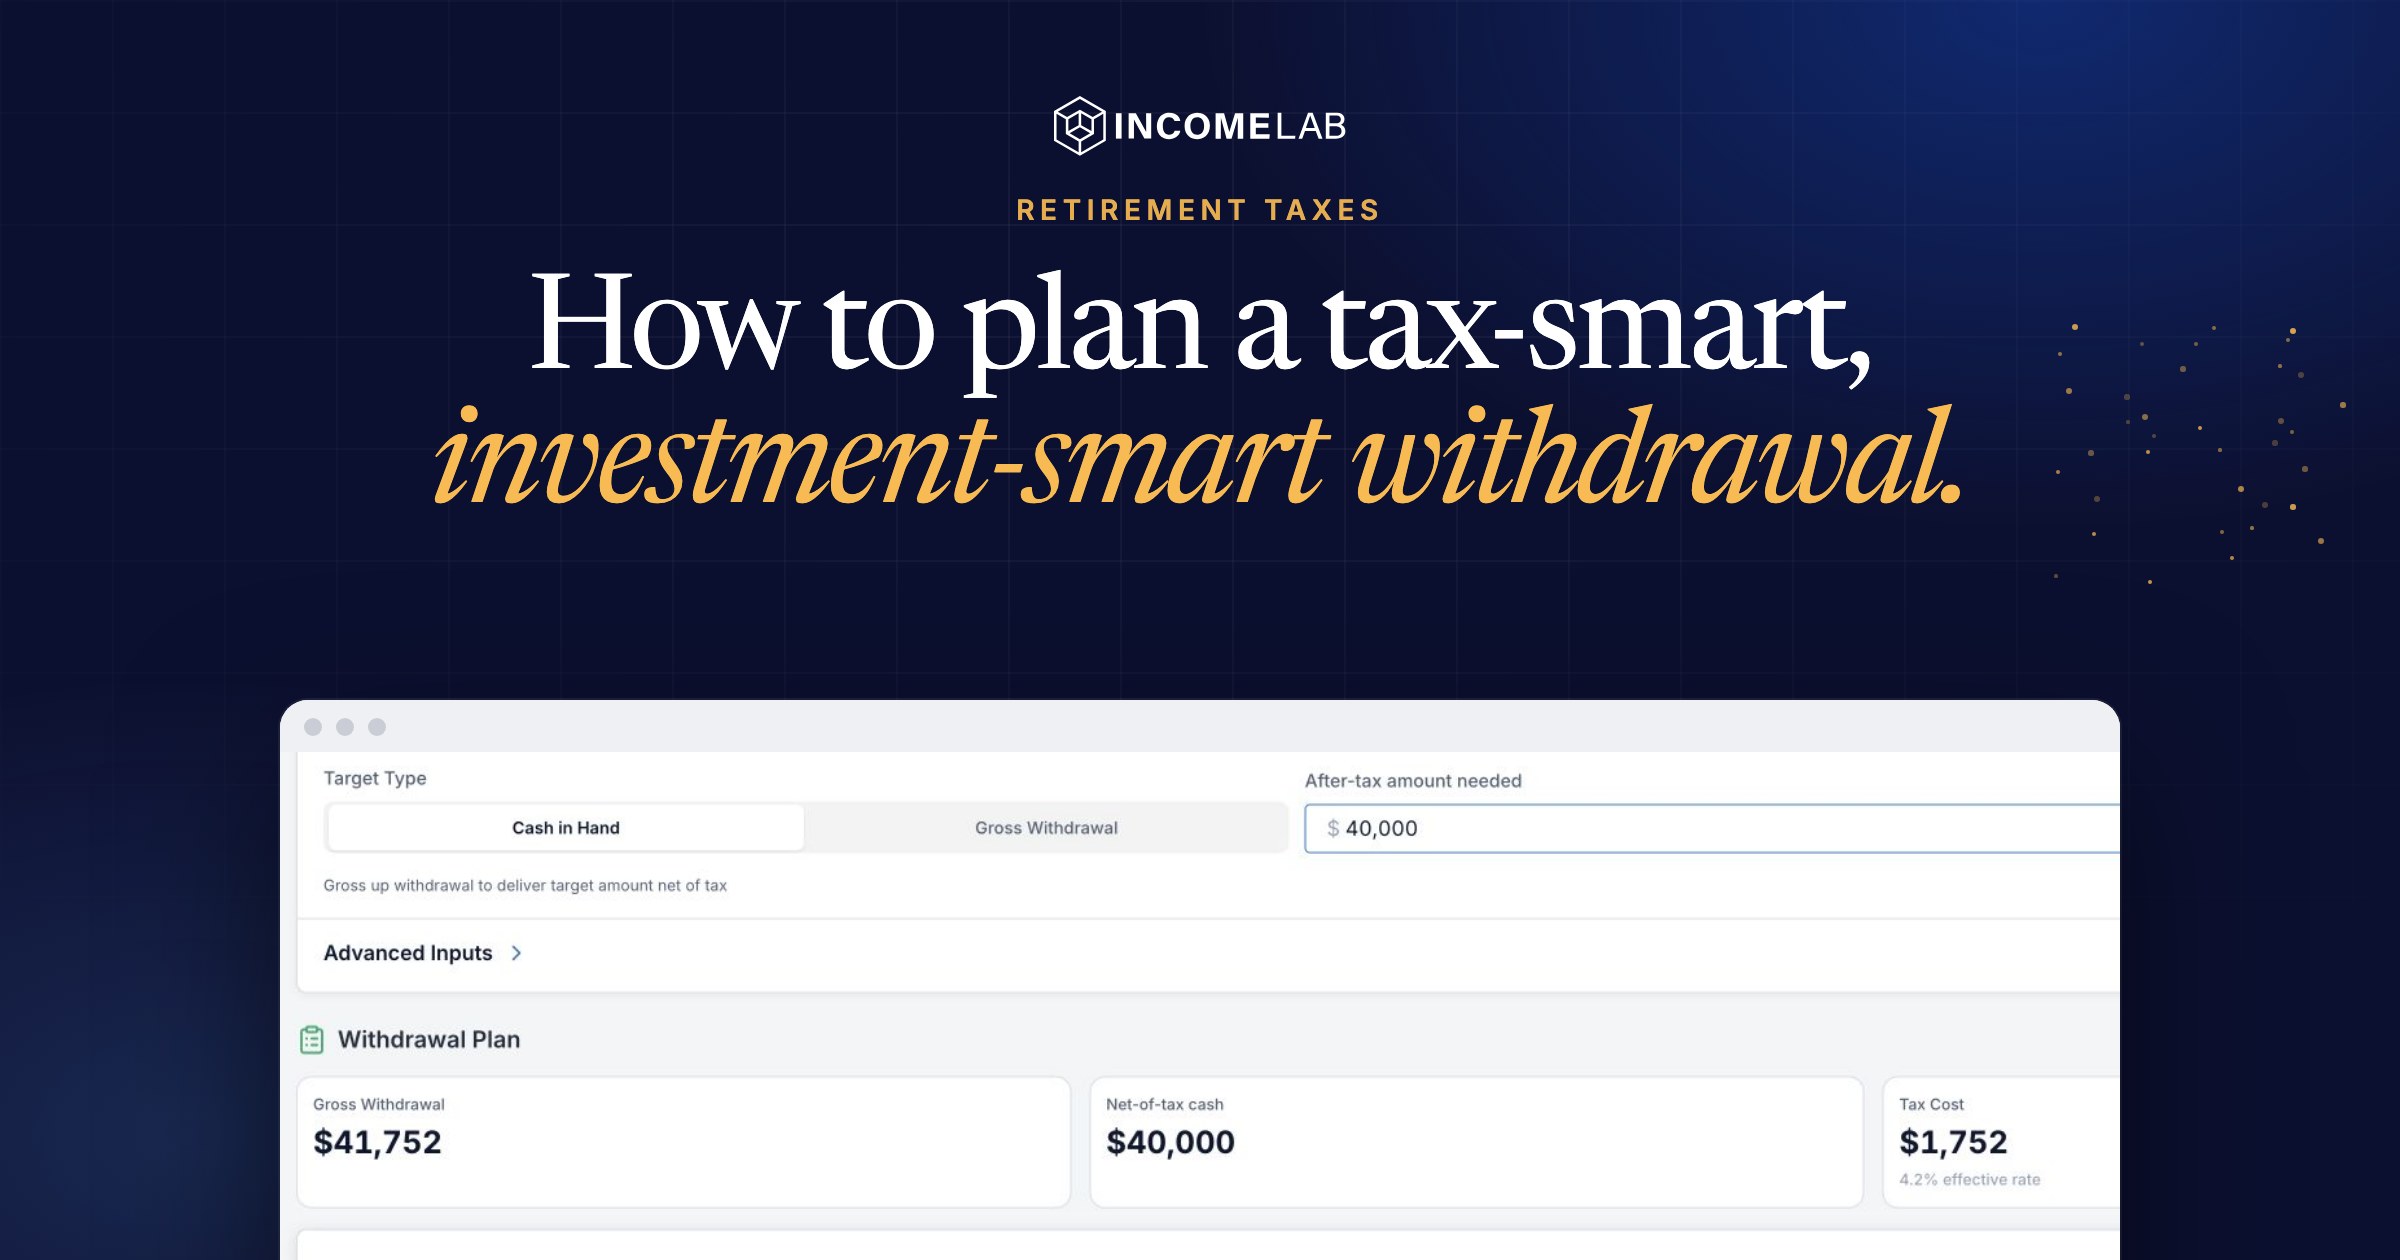
Income Lab’s Withdrawal Optimizer in Penny starts with the client’s financial plan, including the current-year tax picture and withdrawals already contemplated in the plan. It combines that information with account and holding data to calculate how a specific cash request could be funded.
The advisor can enter a target amount of spendable cash (“Cash in Hand”) or specify a gross withdrawal. With a net-cash target, the tool estimates the required gross amounts and related taxes. Withholding can be set to cover the estimated incremental tax, meet a safe-harbor minimum, or leave taxes to separate payments. These choices change how much must be distributed and how the funds are routed.
The proposed withdrawal identifies accounts and holdings, estimated gains and losses, and federal and applicable state withholding. Advisors can exclude accounts or individual holdings, cap sales, set account priorities, and choose tax-optimized sales or pro-rata sales intended to maintain the allocation. Loss and gain harvesting can be enabled or disabled. Additional settings address ordinary-income and long-term capital-gain limits, Medicare and ACA MAGI thresholds, RMDs, standing withholding preferences, and charitable gifts.
The Withdrawal Optimizer also calls out per-account withholding amounts along with federal and state estimated payments and due dates, making the withdrawal recipe an all-in-one set of actions ready for execution.
The tool does not place trades, transfer funds, remit estimated taxes, or execute custodian instructions. The advisor reviews the proposed transactions and implements them through the appropriate accounts and custodians.
This is an area where investment information and planning information are often separated. A tax return alone cannot determine which tax lot to sell, and a holdings report alone cannot show the effect on the client’s total income, tax thresholds, or planned distributions. Bringing those data together makes the cash decision more informed and repeatable.
Common issues to check before the money moves
These questions are useful whether the work is done with software or manually:
-
Is the requested amount gross or net of taxes? A $60,000 distribution and $60,000 in spendable cash can require very different transactions.
-
Are there tax thresholds nearby? Medicare uses a two-year lookback, and tax brackets, gains rates, and credits may change with incremental income.
-
How will taxes actually be paid? Withholding percentages are payment instructions, not the client’s final tax rate.
-
Are estimated tax payments needed? If so, how much and when are they due?
-
Which tax lots should be sold? Gains, losses, position limits, and cost basis can change the answer substantially.
Frequently asked questions
How should an advisor decide where to take a client’s withdrawal from?
Start with the cash amount needed, the client’s current-year plan, and the available accounts and holdings. Compare feasible combinations based on incremental taxes, investment constraints, planned distributions, and the effect on what remains invested. The outcome may involve multiple accounts and specific tax lots.
How is a one-time cash request different from ongoing retirement withdrawals?
A one-time request calls for tactical decisions within the current plan, including holdings to sell, withholding, and the effect on this year’s taxable income. It should still be evaluated in light of longer-term objectives. Ongoing retirement income adds a recurring, multi-year funding problem.
Why can Medicare premiums be affected by a withdrawal?
An additional taxable distribution or realized gain may increase Medicare MAGI above an IRMAA threshold. Medicare ordinarily looks back two years. The exact premiums depend on the schedule in the future premium year, so published current-year amounts are illustrative rather than a forecast.
When would using Roth assets make sense?
Qualified Roth withdrawals can be useful when they allow the client to meet a cash need without pushing other income across a costly threshold that would trigger new taxes or eliminate credits and deductions.
Can a large one-time withdrawal qualify as a Medicare life-changing event?
A withdrawal by itself is generally not one of the life-changing events recognized by Social Security for an IRMAA income adjustment. Advisors should assess the applicable rules and any separate qualifying event before relying on a premium reduction.
Sources
-
IRS, Publication 590-B, Distributions from Individual Retirement Arrangements: irs.gov/publications/p590b
-
IRS, Topic No. 409, Capital Gains and Losses: irs.gov/taxtopics/tc409
-
CMS, 2026 Medicare Parts A and B Premiums and Deductibles (the IRMAA schedule set on the two-year MAGI lookback): cms.gov
-
Medicare, Medicare costs, current Part B and Part D amounts: medicare.gov/basics/costs/medicare-costs
-
Income Lab, “How does Penny’s Withdrawal Optimizer work?”: help.incomelaboratory.com/penny/plan-a-withdrawal-in-penny
-
Social Security Administration, Medicare premiums and rules for higher-income beneficiaries: ssa.gov/benefits/medicare/medicare-premiums
Related reading
-
See a demonstration of a cash withdrawal planned across accounts and holdings.
Figures are hypothetical and use simplified federal tax assumptions and the published 2026 Medicare schedule. Actual taxes, future Medicare premiums, and suitable trades depend on the client’s circumstances.
Continue Reading
Ready to see this in action?
Watch how Income Lab helps advisors answer clients' toughest retirement income questions with guardrails-based planning.
Book a Walkthrough Start Free Trial