
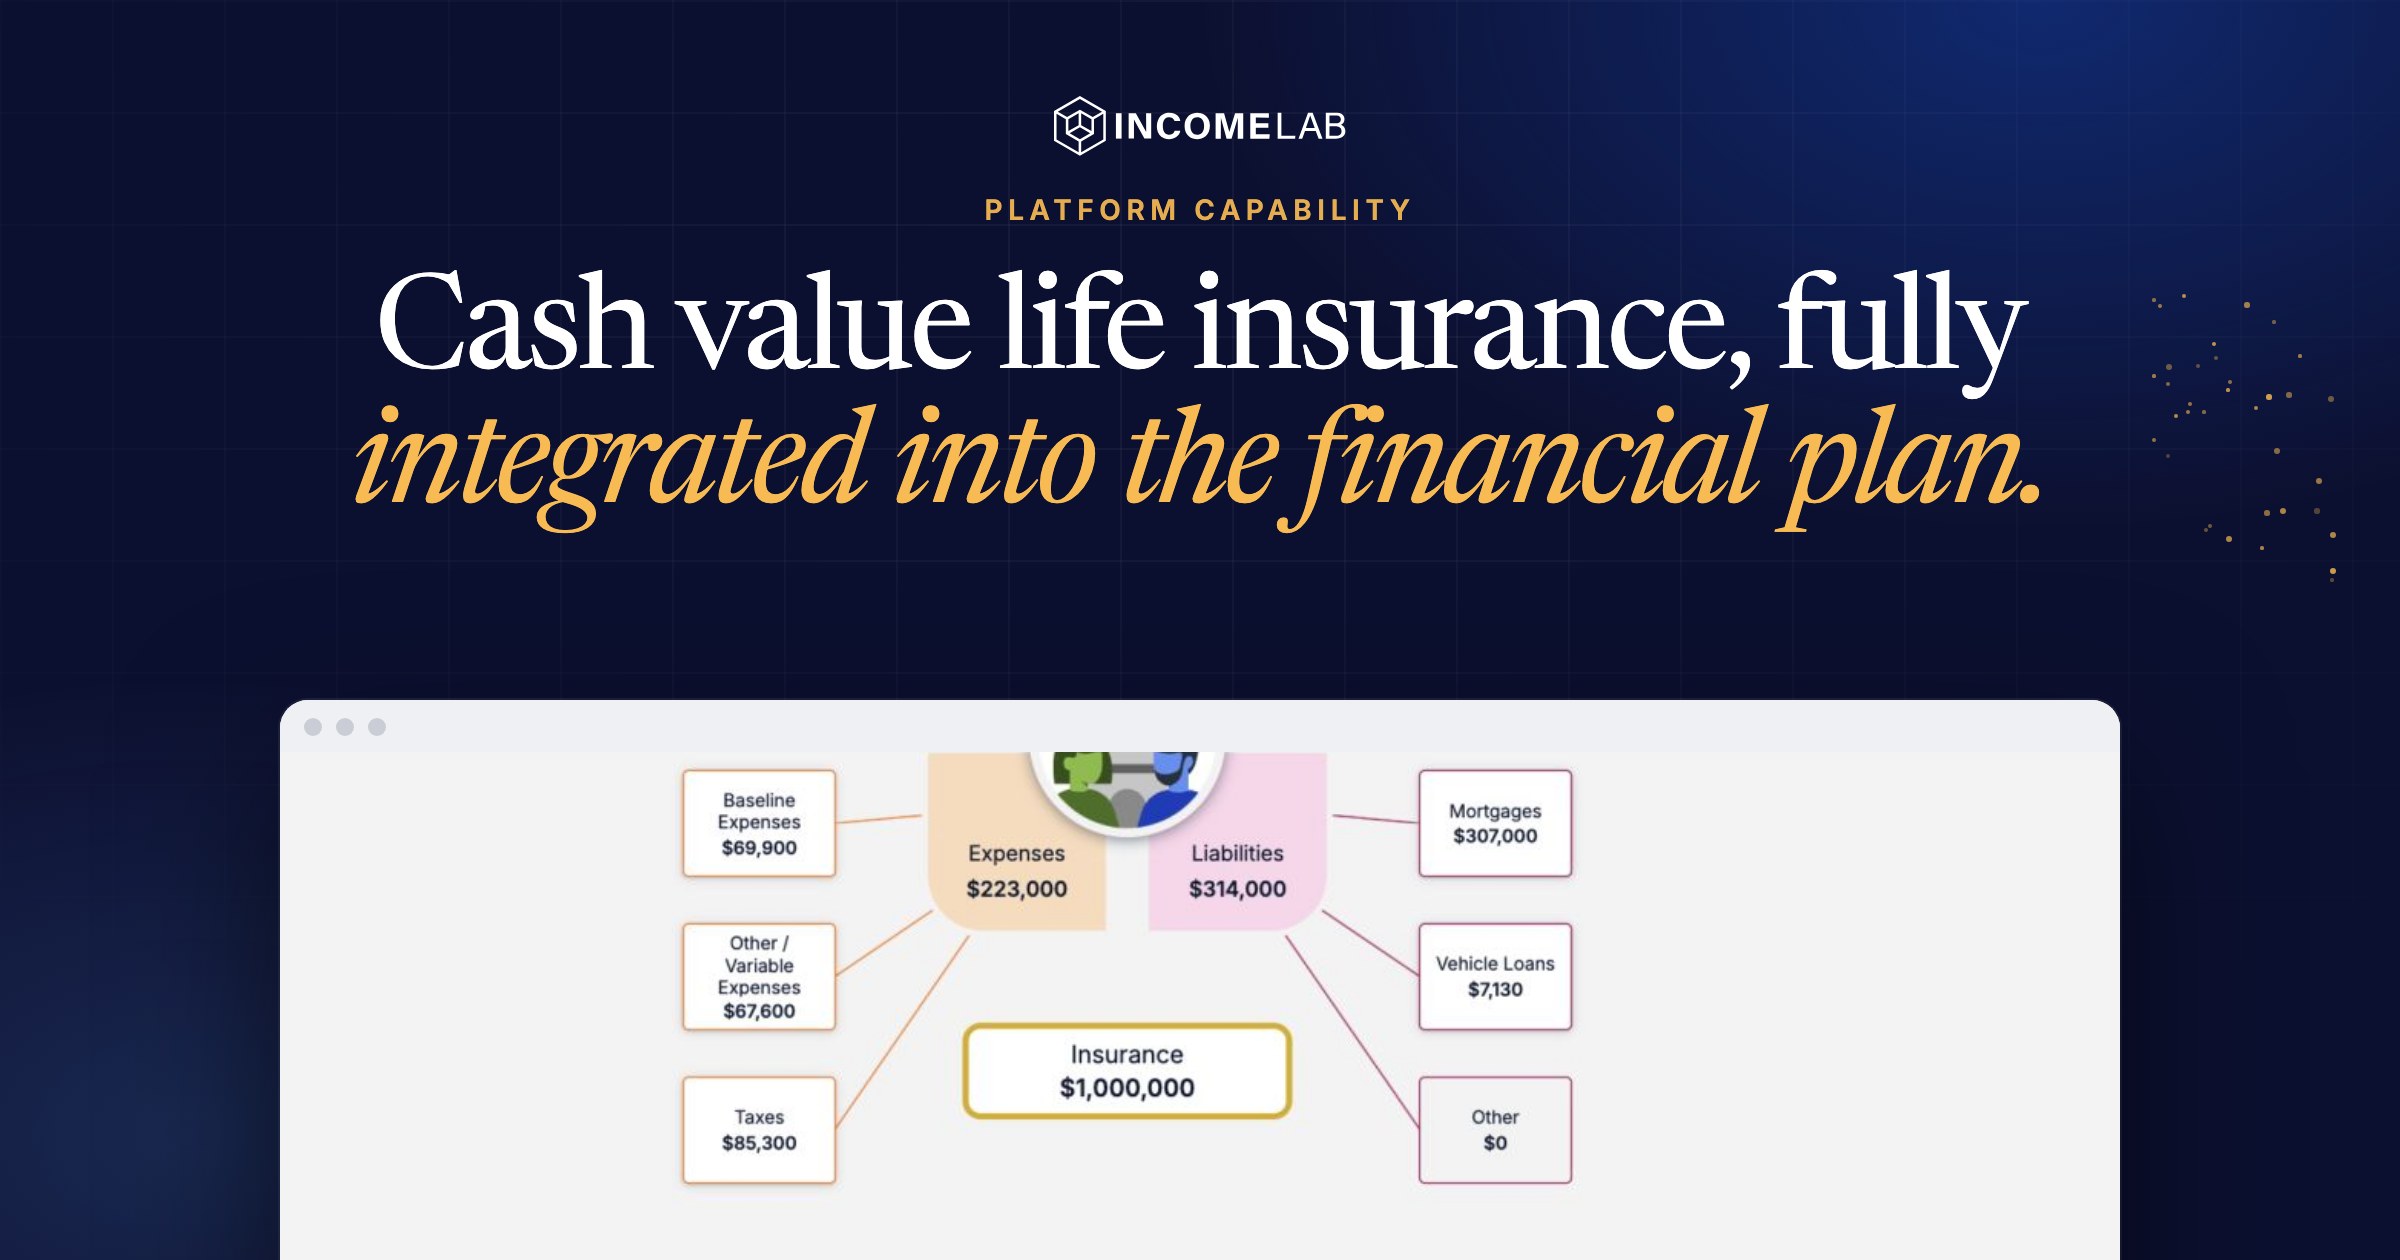
Cash value life insurance can have a substantial effect on a client’s financial plan. Premiums require funding, cash value changes over time, and loans or withdrawals can help support spending. The death benefit also affects the client’s legacy. Income Lab models these moving parts together, using assumptions that reflect the type of policy and connecting the results to the rest of the household’s plan.
Why cash value life insurance is hard to model well
A client arrives with a whole life policy purchased fifteen years ago. The advisor can enter the current cash value in many planning tools, but that may be as far as the integration goes. Future growth is approximated as if the policy were an ordinary investment account. Premiums are entered separately as an expense. The death benefit is tracked elsewhere, and the advisor may have to construct a series of manual adjustments to represent tax-sensitive loans or withdrawals. Even when those workarounds are possible, keeping them consistent as the plan changes takes time.
A policy has several connected financial effects. Premiums affect available cash flow; crediting, investment performance, and charges affect cash value; cash value and loans can affect the death benefit; and the way money is withdrawn can change its tax treatment. Those effects matter to decisions about retirement income, spending, taxes, and legacy. Treating the policy as a static asset, or maintaining separate assumptions in multiple places, can distort the analysis.
Income Lab models those relationships together. For market-linked policies, the modeling can also draw on the same capital market assumptions used elsewhere in the plan. Advisors can evaluate the policy in the context of a household’s other assets, income, expenses, and goals without rebuilding the analysis in a separate spreadsheet.
What Income Lab models, policy type by policy type
Five cash value policy types support detailed growth and distribution modeling. Term life insurance can also be included for its death benefit, without a cash value component.
| Policy type | Cash value growth modeled | Distributions modeled |
|---|---|---|
| Whole Life | Guaranteed cash value growth, plus non-guaranteed dividends | Yes |
| Universal Life (UL) | Credited interest | Yes |
| Indexed Universal Life (IUL) | Index-linked interest with caps, participation rates, or fixed crediting | Yes |
| Variable Universal Life (VUL) | Subaccount investment performance | Yes |
| Variable Life (VL) | Subaccount investment performance | Yes |
| Term Life | No cash value to model | No |
The modeled mechanics vary by policy type. Whole life supports guaranteed cash value growth and optional non-guaranteed dividends. Universal life uses credited interest. Indexed universal life supports fixed crediting and index-linked approaches with caps and participation rates, including blended methods and changes over time. Variable policies allocate cash value across asset classes, so modeled investment performance and applicable fees affect policy values. These distinctions help the projection reflect the actual policy rather than a generic growth assumption.
Premiums, charges, and policy behavior
Advisors can enter monthly, quarterly, semiannual, annual, and one-time premiums. Those amounts flow through the household’s planned expenses. The model can also reflect a decision to stop paying future premiums.
Available fee inputs include premium loads, cost of insurance, administrative charges, rider charges, per-thousand charges, mortality and expense charges, and fund expenses, as applicable to the policy type. Cost of insurance can be entered as a monthly charge per $1,000 of net amount at risk. For example, a $400,000 death benefit and $300,000 cash value produce $100,000 of net amount at risk; a charge of $0.40 per $1,000 would be $40 for that month. These inputs allow a more realistic planning projection while remaining simpler than a carrier’s full contract administration model.
The carrier illustration and policy documents remain essential sources for crediting assumptions, charges, and contractual terms. Some costs, including age-varying cost-of-insurance schedules, are simplified in the planning model. Income Lab is designed to incorporate the economic effects of the policy into a financial plan, rather than reproduce a carrier illustration precisely.
Policy distributions and their tax consequences
An advisor can model distributions over one or two phases, using amounts, percentages, or a stretch approach. The withdrawal method matters because the policy’s tax basis, loan balance, and modified endowment contract (MEC) status can affect the tax result. Available approaches include:
- Policy loans, with a settable loan interest rate and a choice of whether interest is paid from the cash balance or accrues on the loan.
- Cash balance withdrawals.
- Basis-first distributions followed by policy loans, with the tax treatment dependent on the policy’s status and applicable rules.
A cash value floor can limit modeled distributions when the projected balance reaches an advisor-selected minimum. It is a planning constraint on distributions, not a contractual protection against lapse or other policy risks.
The modeled distributions feed into the client’s income sourcing, tax results, spending calculations, and visuals such as Life Hub and Fin Flow. An advisor can therefore test a proposal to draw $2,000 per month from a policy for ten years and see the effect alongside other income sources and portfolio withdrawals.
Additional inputs include MEC status, policy anniversary month, insured life, maturity age, death benefit option, tax corridor, cost basis, and premiums paid. These details matter to how the policy behaves over the life of the plan.
Example: using a policy to bridge retirement income
Consider a hypothetical client who wants to use an existing life insurance policy to help cover expenses during the first years of retirement.
Carol is 62 and expects to retire at 65. She owns a universal life policy with a $400,000 death benefit, $118,000 in cash value, $6,000 in annual premiums, and $92,000 in recorded basis. Her advisor enters those values, together with the policy’s crediting assumptions and available charge information. The premiums appear in her projected cash flows through age 65.
Carol is considering claiming Social Security at 70 and wants to know whether the policy could help fund the five-year gap after retirement. Her advisor models distributions from age 65 through 69, using the basis-first-then-loans option and a cash value floor. The projection shows the effect on remaining policy value and death benefit and the resulting change in other withdrawals required from her portfolio. It also shows that Carol’s retirement paycheck goes up and her lower guardrail (where a reduction in spending would be called for) goes down, meaning a pay cut is less likely. The advisor can then review the tax assumptions and compare this scenario with alternatives that leave the policy untouched or change the distribution amount.
This analysis makes the policy’s role in Carol’s plan measurable. Drawing on cash value may reduce near-term portfolio withdrawals, while also affecting future policy values, loan balances, and the amount available for beneficiaries. The advisor can evaluate those consequences using the same plan assumptions that support the rest of Carol’s retirement analysis.
The accuracy of the illustration depends on the policy information available. Advisors should use current statements and illustrations to check cash value, basis, premiums, crediting terms, and charges, particularly before recommending a distribution strategy.
A part of the financial plan, not a separate calculation
The value of this modeling is in its integration. A policy’s premiums affect the household’s spending resources. Cash value growth and charges affect projected assets. Distributions can reduce the need for portfolio withdrawals, with consequences for income taxes and future account balances. Death benefits affect legacy projections. Those results carry through to the plan’s spending analysis, Tax Lab, and client-facing views in Life Hub and Fin Flow. Advisors can change assumptions and evaluate a different strategy without manually reconciling multiple schedules or spreadsheets.
There are boundaries to the model. Income Lab does not model surrender charges and also simplifies some contract-specific costs. An advisor considering distributions during a surrender-charge period, or a strategy that could create a risk of policy lapse and taxable gain, should review the actual contract and carrier projections alongside the financial plan.
Frequently asked questions
Can Income Lab model a whole life policy’s cash value within a financial plan?
Yes. The model can include guaranteed cash value growth, non-guaranteed dividends, premiums, relevant charges, and distributions. Those projected cash flows and policy values are integrated with the household’s other assets, expenses, taxes, and spending needs.
How are life insurance loans and withdrawals modeled for tax purposes?
Advisors can model policy loans, cash value withdrawals, and a basis-first-then-loans approach. The model includes inputs for tax basis, premiums paid, and MEC status. Actual tax results depend on the policy and circumstances: MEC distributions and loans have different tax rules, and a lapse or surrender with an outstanding loan can create taxable income. Advisors should confirm contract-specific treatment before implementing a strategy.
Can Income Lab model indexed universal life crediting?
Yes. Indexed universal life can use caps, participation rates, fixed crediting, and combinations that change over time. The assumptions can reference a built-in index or a custom blend of asset classes, allowing the advisor to evaluate the policy with assumptions connected to the rest of the plan.
Does Income Lab replace a carrier illustration?
No. Carrier illustrations and policy documents supply contract details and remain important for validating a proposed strategy. Income Lab models a policy’s expected financial effects within the broader plan; it does not reproduce every contractual charge or guarantee, and it does not currently model surrender charges.
Does this modeling determine how much life insurance a client needs?
No. The capability models existing or proposed policies and their effects on the financial plan. Coverage-needs analysis is a separate task. Advisors can use the results alongside their insurance analysis when evaluating whether to retain, adjust, or replace a policy.
See the policy in the context of the whole plan
Bring a client’s policy details to a walkthrough. We can show how premiums, cash value, loans or withdrawals, and death benefits affect the household’s spending plan, taxes, and legacy projections, all within Income Lab.
Related reading
Sources
- Income Lab Help Center, “How to model cash value life insurance,” originally published September 15, 2026, revised September 24, 2026 (adding an embedded walkthrough video and transcript), re-read against this page September 30, 2026: help.incomelaboratory.com. A walkthrough video of the modeling is embedded in that article.
- IRS, Life insurance and disability insurance proceeds: irs.gov
- IRS, Publication 525, Taxable and Nontaxable Income (life insurance surrender and withdrawal treatment): irs.gov/publications/p525
Continue Reading
Ready to see this in action?
Watch how Income Lab helps advisors answer clients' toughest retirement income questions with guardrails-based planning.
Book a Walkthrough Start Free Trial